
PPI Market Vision 2030: ₹136-227 Trillion Opportunity - Here's Your Strategic Roadmap
PPI Market Vision 2030: ₹136-227 Trillion Opportunity - Here's Your Strategic Roadmap
Introduction
Here's what Wall Street and VCs are missing about India's digital payments opportunity: While everyone obsesses over UPI's 15+ billion monthly transactions, a ₹227 trillion alternative ecosystem is being quietly built by PPIs through embedded lending, B2B payments, and specialized verticals.
What are PPIs?
Prepaid Payment Instruments are digital wallets, prepaid cards, and stored-value products issued by banks and fintechs. Unlike debit cards (linked to accounts), PPIs store preloaded funds and can be used across merchants, online platforms, and ATMs. India has 1.35 billion active PPIs (86.8 crore wallets + 48.4 crore cards) as of FY25. [Economic Times]
The UPI Interoperability Shift
In July 2025, RBI mandated all full-KYC PPIs to integrate with UPI, transforming isolated wallets into interoperable digital payment accounts. This has reshaped the competitive landscape—PPIs can no longer compete on generic wallet features; they must specialize in verticals (corporate gifting, embedded lending, B2B, travel) where they add unique value.
Current Market Scale
India's digital payment ecosystem processes ₹299 trillion in annual value (FY25) across 206 billion transactions. PPIs currently handle approximately ₹5 trillion of this—representing a foundational but nascent segment. [PWC]
The ₹227 Trillion Opportunity
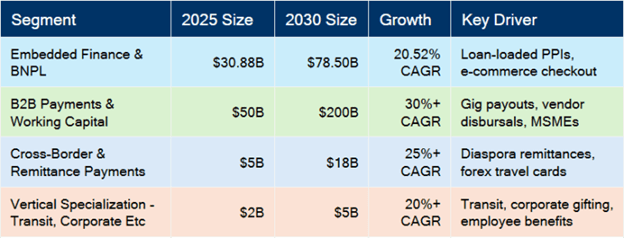
Following table describing the real opportunity in different segments.
Sources:
Strategic Imperatives: Key stakeholders
For PPI Issuers & FinTechs
- Embed lending, don't compete on wallets: BNPL + credit scoring = moat (sustainable competitive advantage)
- Invest in AI + real-time data: Credit decisioning + fraud detection = margin protection
- Prioritize compliance excellence: RBI's tightening = barrier to entry for competitors
- Sustainability: Sustainability becomes a brand differentiator by 2027
For Businesses & Platforms
-
Embed PPIs into checkout & payroll (Capture payment economics + deepen engagement simultaneously)
-
Evaluate proprietary PPI licensing (Unlock revenue streams + customer data moat for GMV >₹1,000 Cr)
For Regulators & Policymakers
-
Clarify embedded lending rules (Guidance on BNPL, loan-loaded PPIs unlocks ₹26T opportunity)
-
Enable cross-border PPI corridors (Clear frameworks fuel growth in diaspora & B2B exports)
-
Advance sustainability standards (ESG-linked payments position India as global fintech leader)
M&A & Investment Catalysts
The PPI ecosystem will see significant consolidation and venture capital activity:
-
VC funding: USD 5–10B flows to embedded finance & BNPL FinTechs by 2030. [Enter Slice]
-
Strategic M&A: PPI license acquisitions surge, especially platforms with embedded lending
-
Public listings: 2–3 PPI-led/integrated FinTechs expected to IPO by 2030, targeting $500B+ cumulative value. [Economic Times]
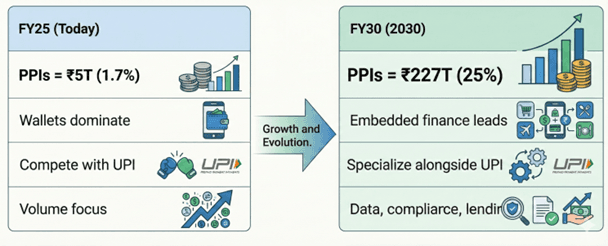
Now vs. 2030: Transformation Snapshot
The Strategic Question?
₹227T in PPI-powered payments by 2030 isn’t a forecast—it’s the destination.
Are you building for 2030… or defending 2025?
Winners will:
-
Embed lending, insurance, and personalization into PPIs
-
Specialize in B2B, travel, gig economy verticals
-
Lead on compliance, sustainability, and AI-driven risk
Time to move: NOW - not 2027.
About the Author
Ajit Maya
Ajit Maya explores India’s fast-changing fintech space. From PPIs to UPI and emerging tech, he breaks down complex ideas into simple, useful insights for everyday readers and fintech lovers.
About the Author
Ajit Maya
Ajit Maya explores India’s fast-changing fintech space. From PPIs to UPI and emerging tech, he breaks down complex ideas into simple, useful insights for everyday readers and fintech lovers.